 Go to Learning Platform
 Support
 My Account


Availability
In-StockISBN
Digital: 5-year license - 978-1-62542-865-3Currency
All prices shown in USDDigital Terms
Click here to view our digital terms.A new product will be added to your cart each time you click the Product button. If additional options exist (checkboxes) to further customize your product and you'd like to choose one of the them, please select the option before clicking the product button to add to your cart. Click here to edit your cart.
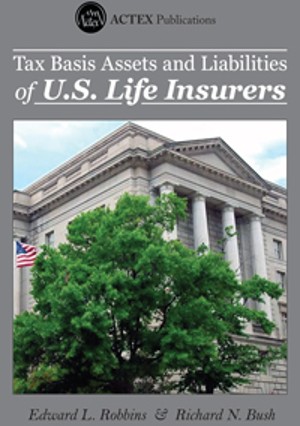
Overview of Tax Basis Accounting for U.S. Life Insurers
This sequel to U.S. Tax Reserves for Life Insurers, published in 2005, provides authoritative guidance and mathematical approaches for calculating actuarial tax-basis liabilities, including reserves and related items, as well as assets, primarily invested assets and deferred taxes.
The book introduces statutory and tax reserve planning and provides a detailed discussion of the relevant authoritative guidance, including extensive references to specific cases and rulings. It also offers an in-depth treatment of investment tax accounting and an introduction to the tax aspects of business combinations.
The Book's Organization
The first nine chapters establish the foundation for understanding tax reserves and their relationship to statutory reserves. The discussion begins with the economic rationale for reserves and the fundamentals of the insurance business before moving into specific statutory reserve requirements and the structure and taxation of tax reserves.
Chapter 1 discusses the economic reasons for reserves and provides an overview of statutory reserving principles.
Chapters 2–9 examine the structure of tax reserves and their effects on taxable income, while describing the similarities and differences between tax reserves and statutory reserves.
Chapter 10 introduces tax reserve planning and documentation. It also covers related topics, including proxy deferred acquisition cost capitalization and amortization, statutory deferred tax assets, and required capital.
Chapter 11 covers investment tax accounting and is the longest chapter in the book. It addresses invested assets held and derivatives entered into by life insurance companies in general.
Chapter 12 addresses special reserving issues for accident and health contracts. Because the 1984 Tax Act focused primarily on life insurance and annuity products, accident and health contracts require separate consideration.
Chapter 13 updates the original book with significant additional information on the tax aspects of business combinations.
Chapter 14 provides a detailed discussion of the tax aspects of separate accounts of life insurers, including transactions between general and separate accounts and the application of IRC Section 817.
Chapter 15 covers Modified Guaranteed Contracts, a specialized area governed by IRC Section 817A and subject to regulations separate from the general statutory guidance.
